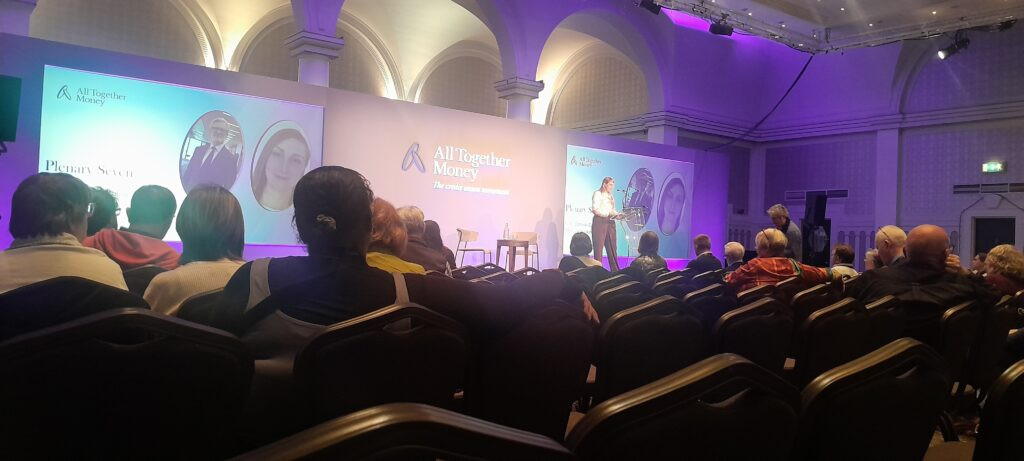
UK credit unions apex All Together Money met last weekend for its first national conference since its rebrand – with the focus firmly on growth, in line with the government’s ambition to double the national co-operative and mutual economy.
Coventry Building Society’s Glenn Bemment told delegates at the start of the two-day event, held in Leeds from 11-12 September, that the government’s pledge “is an important focal point but the prize is not a statistic”.
Rather, the end goal is a fairer, more stable and sustainable economy, he said, paying tribute to the mutual values of the Coventry and its recent acquisition, the Co-operative Bank. “‘In a mutual financial strength is not the destination,” he added, “it’s an enabler of so much more.”
Growth means more opportunities for financial inclusion, and the delivery of fair and transparent services from organisations – including credit unions – that understand people’s needs, he said.
Rose Marley, CEO of Co-operatives UK, also saluted the values of the democratic economy – which generates more than £179bn for the UK. This money, she said, stays in the country – often in the community where it is generated.
Improving public knowledge of the model is key to growing the democratic economy, she said. “We need to communicate that we are the good growth our prime minister is talking about,” she said.
And there is scope for credit unions to benefit from and help drive the sector’s growth, added Marley, by working with Co-op Academies, and with co-ops in the health and social care sector.
It could also be helpful if credit union representatives served on the neighbourhood boards of the government’s Pride In Place programme, she argued. This is an attempt to deliver funding for grassroots projects in “left-behind” communities, but concerns have been raised that some projects are being run locally on a top-down basis, with business leaders and councillors taking over.
“A lot of organisations don’t know how to do democracy,” said Marley, “they haven’t done it so long … We need to have the people on board.”
If credit unions can offer quick wins, she added, national government and regional mayors will be receptive.
Related: How do you give away power? The tricky question for Pride in Place
In terms of communicating the credit union message, Mike Pye, managing director of marketing firm MP&Co, led a session on the merits of rebranding and relaunching.
MP&Co has been working with credit unions for 20 years, said Pye. “They ask questions like, should we rename, should we rebrand, and they tell us that no one understands what a credit union is. The danger is that they’ll spend more time explaining that, rather than telling what they can do for their members.”
But the problem remains that the public does not understand what credit unions are – and this is a barrier to growth. The questions here, added Pye, are: “What don’t they understand? How do we help make their understanding better?”
This, said Pye, means explaining what a credit unions can do for members, how they are different from banks, who is eligible for membership, and why people should choose one.
“Whether you are relevant is a positioning and messaging challenge,” he said.
Those challenges include the need to make it clear that credit unions are not just a “poor man’s bank” –when they often have to create products and messaging for “people in urgent need”.
It is also important to establish trust – and professional branding is vital here, said Pye. “We see organisations with fantastic values, a great team, let down by branding,” he said. “I’m talking about the whole experience a member has with you – messaging, website, the way you talk, the language you use, the way you visually illustrate things. Trust is key.”
A weak visual identity can make a credit union look less trustworthy, he warned, and credit unions need to offer a digital experience that matches those of banks and online lenders.
“Before you think about brand, think about the challenge you face. Is it that you don’t reach enough people? Is it that they don’t understand?”
This feeds in to the question of whether a credit union should rebrand, with a new website, social channels and visual identity, or fully change their name – perhaps by dropping the term ‘credit union’ altogether.
“It’s not necessarily a right or wrong answer,” said Pye. “It’s a deeper question than ‘should we rename as a community bank’.”
And a name change alone is not enough: the relaunched Castle Community Bank in Scotland got its messaging right, said Pye – this “homes in quickly on savings and loans, the website gets it right in on what they offer”.
And with an attractive brand identity in terms of colour palette and signage, it “looks trustworthy”: with 76,000 members, it has “successfully managed awareness”.
On other hand, Glasgow Credit Union kept the term – but again. “the messaging is well done, it speaks the language of local people”.
Related: Lender drops credit union name to rebrand as Northern Community Bank
The “community bank” branding may be broader and more mainstream, said Pye, but needs more effort to explain in terms of difference and ethos, and there is potential loss of heritage. “Members are very aligned to the ‘credit union’ term,” he warned. “One credit union changed to the community bank name – and members thought it had demutualised, that they couldn’t be members any more, and had trust concerns, because they hadn’t done member communication right.”
But the “credit union” label also carries misconceptions and a burden of explanation, with the need to dissociate it from bad associations with the term “credit” and to make clear they are not just for trade union members..
There’s also the all-important question of attracting young members. “Think about cultural trends, educational trends, the language and channels you use,” said Pye. “Are people still reading blogs on your website or are they using AI and Tik-Tok? Are they still on Instagram?”
Youth is not the only social group relevant to credit unions: inclusion is a priority for the movement, and the conference saw a presentation by Reg Cobb, CEO of support and advice organisation Deafplus.
Cobb discussed the Deaf Equity in Financial Services Report 2026, delivered in partnership with Nationwide, which explored the barriers facing deaf customers, and the practical steps organisations can take to create more inclusive and accessible services.
An obvious way to drive inclusion is to book BSL interpreters – and Cobb delivered his speech in BSL, with two interpreters translating to speech.
But this is not enough, he warned: there is a “hidden and huge” language barrier facing deaf customers. Around 90% of deaf people born into hearing families – and, said Cobb, for the first three years of their lives they often have no access to language.
This can lead to difficulties with English comprehension: 70% of deaf people don’t know how to use the information given to them by an interpreter, said Cobb. This can lead to a lack of agency, with decisions taken for deaf customers by the hearing person who is interpreting for them.
Credit unions should be aware of these risks, said Cobb, as well as the vulnerability of deaf customers to scams. “There is an unbelievable number of people struggling out there,” he said.
Growth is not just a matter of individual credit unions: it also demands a movement-wide strategy. Paul Jones and Nick Money of the Swoboda Research Centre gave an update on a research project to develop a new vision for the sector. Work on this is being led by Swoboda with the New Economics Foundation, and a survey has attracted 226 full responses from CEOs, non CEOs, and credit unions of all sizes.
Related: Swoboda and NEF look for a new vision for UK credit unions
The purpose, said Money, is “to help us understand and plan what we might do for the future”.
Presenting the results, Jones noted differences of opinion between larger and smaller credit unions. Asked to identify challenges facing the sector, the key factor cited in the survey is lack of awareness – although this is more marked among smaller credit unions. Larger credit unions, on the other hand, are more concerned than smaller ones about the pace of technological change.
Smaller credit unions are more concerned about finding competent board members; larger ones are more concerned about relevance.
“In general,” said Jones, “larger credit unions and CEOs are much more confident about their own institutions, more optimistic about growth – but also the sector’s sharpest critics of its collective national performance.
“Smaller credit unions and non-CEOs share the same ambition for the sector but report tighter resources, a more precarious present, and a more uncertain future.”
Overall, the survey found a lack of confidence in the ability to double the credit union sector – and 76% of CEOs are not satisfied with its national impact of the sector.
There is also a question, added Jones, of what ‘awareness’ means. “Does it depend on the common offer? Does the public know we’re good for savings and for loans? Other people say it doesn’t matter … people like the ethics, values, co-operation.”
Another question is how to achieve scale. The options, said Money, are mergers and collaboration, for instance through a credit union service organisation (cuso) – a route eased in recent legislation.
There are more specific avenues for growth, for instance by offering loans and green mortgages through the Warm Homes Plan, which will enable homeowners to retrofit their property with solar panels, insulation and heat pumps.
With homes being the second highest emitting sectors in the UK, decarbonisation is key to the net zero agenda – but, said Ryan Jude from the Green Finance Institute (GFI), it also feeds into the pledge to double the mutual economy.
“We’re hoping you can design green loans in a way that’s more affordable for the consumer,” he said, noting that with about 60% of unsecured green loans in the UK provided by credit unions, the sector is already taking up the “big opportunity” of the Warm Homes Plan.
The GFI – a non-profit set up by the UK government and the City of London Corporation – works with investors, lenders and the policymakers to mobilise capital, with £15bn available in government grants.
Jude said the GFI highlights its work with credit unions, when speaking to councils and regional mayors, “as another way that we can support local economic growth, with local profits being reinvested in local areas”.
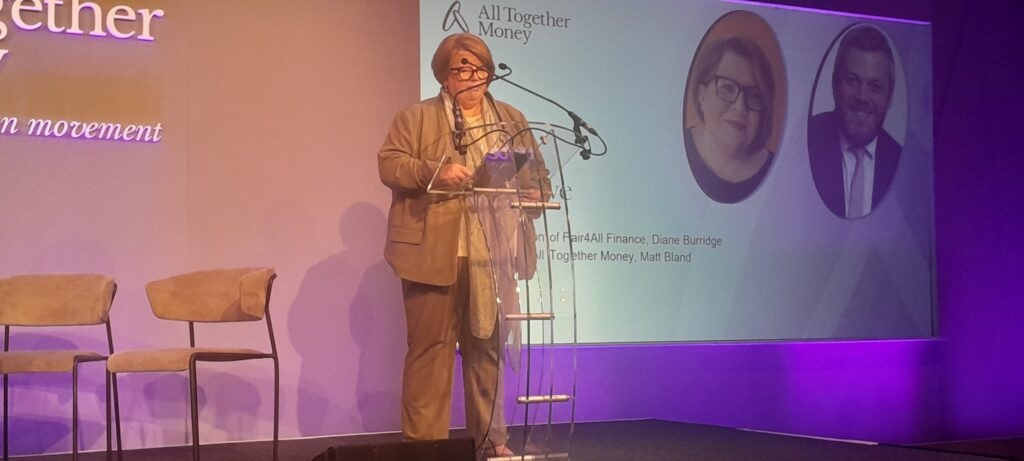
A policy more directly pinned to sector growth is the Credit Union Transformation Fund, which is looking to deploy £30m from dormant assets to modernise and double credit union use in England by 2035.
Kate Pender, CEO of Fair4All Finance, which is delivering the project, said her organisation will be working with All Together Money to develop ideas.
There has been a long consultation process, with roadshows and “challenging” conversations, said Pender. “One thing that’s really struck me throughout is the commitment that people have to serving the members and communities. That’s one of the reasons I’ve become increasingly optimistic about the future of the sector.”
Related: Resilience fund launched for credit unions and other community financers
She added: “The challenge we’re trying to address is that millions of people across the UK still struggle to access fair and affordable financial services. Many people continue to face barriers to affordable credit. Many have limited financial resilience and insufficient savings and protection products that help them manage miles ups and downs. And when we talk about addressing those challenges, credit unions have a hugely important part to play.”
The goal, said Pender, is a sector “that’s equipped to grow, not just in scale, but in capability, in infrastructure, in technology, in collaboration, and its ability to reach people who need affordable financial services”.
Efforts have been made to build flexibility into the programme, she added, after the consultation revealed that “there is no single route to transformation.
“Different organisations serve different communities; they have different strengths and different priorities. Many of these challenged us not to assume that every organisation should follow the same path. One credit union leader put it very simply to me. We’re all trying to get to the same destination, but we’re starting from very different places.”
There are also different priorities and challenges. “Some are already investing heavily in technology. Some are focused on growth. Some are exploring partnership opportunities, and others are managing the immediate challenges of just day-to-day delivery.”
The consultation also pointed – again – to the potential of cusos, said Pender. “Scale doesn’t always come from becoming bigger. Sometimes it comes from doing more together than any organisation would do alone.”
The outcome, she added, is a programme that avoids “one-size-fits-all” solutions. “We’re aiming to support multiple pathways to transformation. For some organisations, that might be technology organisation. For others, it could be shared infrastructure. For others, it may involve multiplicative partnerships, regional operating models, or cusos. And for some, consolidation may be part of the longer-term journey. But in all cases, the destination is shared: a stronger, more sustainable sector with greater impact ”
Cusos are well established in the USA and the conference featured a panel from four US practitioners (main photo) – Miriam Ackerman, founder, and board member at Nacuso, the trade body for cusos; Steve Satzer, from payments fintech cuso Velera; James McBride, from Let’s Go! which supports credit unions looking to grow and challenge banks; and Ray Crouse, from Skyla, a credit union that makes and manages a number of cuso investments.
The panel offered a balanced view of the benefits of the cuso model: it can provide the scale, expertise, and innovation that individual institutions might lack. But they also warned of the financial, regulatory and reputational risks.
It is important, they agreed, to ensure a cuso is properly capitalised from the outset and that issues and governance and regulation are addressed from the get-go. And credit unions should avoid launching a cuso for a cusp’s sake, or duplicating existing services.
The potential rewards are substantial: McBride, noting that UK credit unions are still steering clear of mortgage lending, pointed to a cuso launched in Ohio to facilitate this market; it now serves 200 credit unions across the US.
“That, to me, is a good illustration of the superpower of cusos,” he said.
Another benefit, noted Crouse, is that a cuso can deliver the operational efficiencies and build economies of scale the sector needs without the need for mergers.
McBride agreed, noting that many UK credit unions have stuck close to their roots. “I was almost brought to tears hearing about how close credit unions are to their community,” he said of the UK sector. “That’s something that our industry in the United States, to a degree, has lost.”
Cusos also featured in presentation from Prudential Regulation Authority (PRA)’s Jacqui Ashe and the Financial Regulation Authority (FCA)’s Dominic Cashman.
“Sustainable growth is about building organisations that are resilient enough to keep serving their members for years and decades to come,” said Ashe.
To that end, collaboration through cusos is a crucial way forward, she added. “No individual board or credit union has all of the answers, but collectively, the movement possesses a huge amount of knowledge and experience and capability.
“From a prudential perspective, collaboration can help improve resilience when it allows firms to access expertise, systems, or capabilities that it would be difficult to develop individually. It can promote efficiency. It can remove duplication, and ultimately, it can help firms serve their members more effectively.”
To encourage this, the regulators have lifted the cap on how much capital credit unions are allowed to invest in a cuso – from 5% to 7.5%.
Related: UK regulators promise reforms to help grow financial mutuals sector
Cashman pointed to a time of huge change from the economy, with the acceleration of tech and AI, the rise of challenger financial organisations, and a generational transfer of wealth.
“The threat,” he said, “is that credit unions could lose relevance if you cannot match customers’ expectations of speed, simplicity, and digital access.
“But the opportunity is that the credit union proposition, trust membership, and a focus on responsible finance can be powerfully enhanced by better technology, shared infrastructure, and new partnerships.
“Technology also changes the risk environment.”
A clear example of this is the rise of AI, and the conference closed with a presentation by Matt Howarth of Reason Digital. There are potentially “catastrophic” risks here, he said, notably with the “massive increase in the amount of AI-backed fraud” – as well as the growing danger that AI agents can themselves go rogue.
There is also the risk that reliance on AI will de-skill human operators – so that when the AI fails, human workers will lack the memory-muscle and reflexes to jump in and rescue the situation.
As for how AI is playing out specifically for credit unions, Howarth noted that while traditional banks are using AI for back office functions, credit unions tend to rely on the tech for contact centre work. And this brings benefits: Frontier Credit Union in the US says it can process 70% more loan applications with AI, while employing the exact same number of people.
“We’re also seeing correlation between credit unions that are leading on the use of generative AI being more likely to grow than the ones falling behind,” he added.
Credit unions should also consider adapting their online material to suit a new online landscape, said Howarth, where more and more users of internet searches are relying on AI summaries than website links.
“A lot of people are just skipping websites and going straight to something like ChatGPT and asking for an answer to a question there, such as ‘Hey, are credit unions any good? Are they better than banks?’
“And that might be how they’re trusting it, rather than kind of looking at your website.”
This means that “organisations are now starting to write their website primarily for robots rather than humans,” added Howarth.